Buying
Can an Assumable Loan Help You Sell Your Home? A Seller's Guide to VA and FHA Assumptions
By Mollie Younger October 10, 2026 6 min read
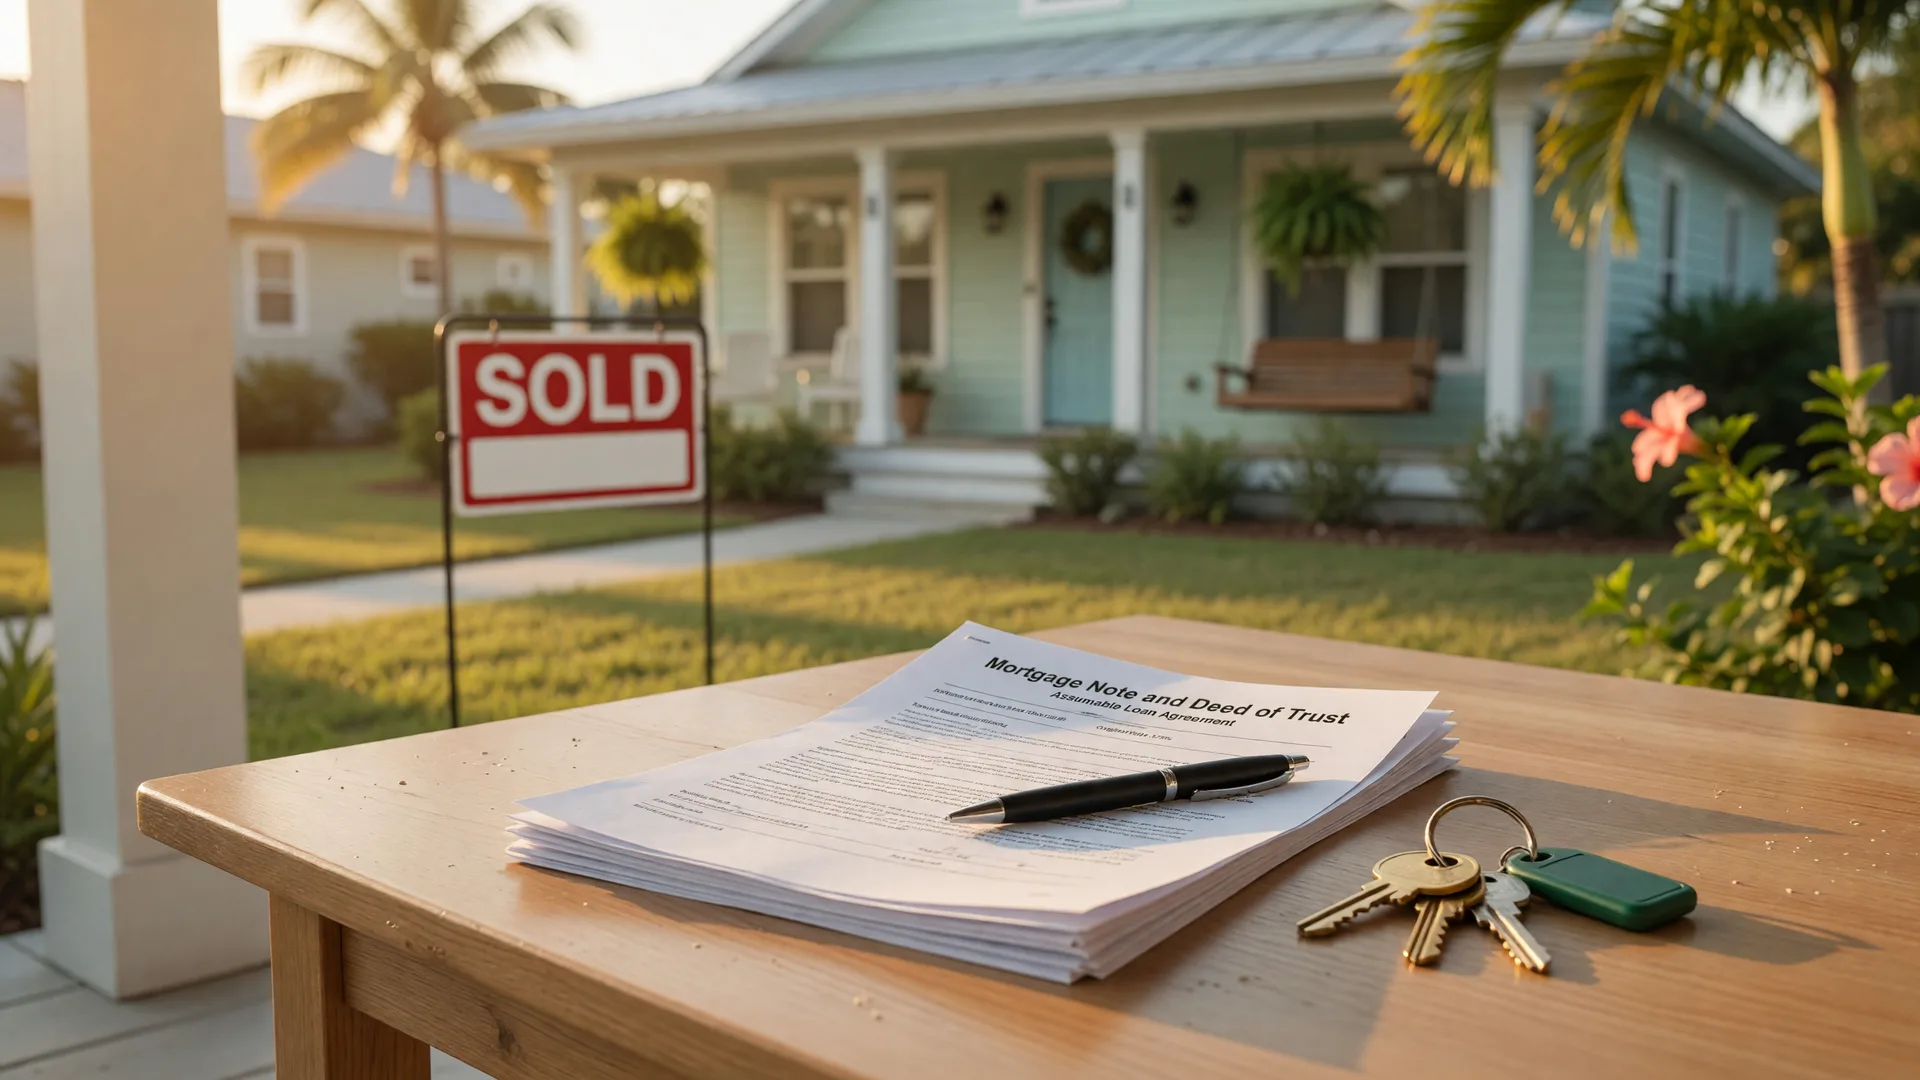
A low-rate VA, FHA, or USDA loan can be a seller's hidden advantage in a higher-rate market. Here is how assumptions work, who qualifies, and the catch to know before you advertise one.
Here's the thing: if you bought or refinanced a few years ago, you may be sitting on a mortgage rate that does not exist in today's market. That low rate is an asset, and most sellers never realize they own it. In a higher-rate market, the ability to hand that rate to a qualified buyer can be the difference between a home that sits and a home that sells. This guide covers what an assumable loan is, which loans qualify, why it can help you sell, and the honest catch to know before you advertise one.
What is an assumable loan?
An assumable loan lets a qualified buyer take over your existing mortgage instead of getting a brand-new one. They step into your rate, your remaining balance, and your remaining terms, with the lender's approval. The buyer does not have to qualify at today's higher rates; they qualify against the loan you already have. That is the whole idea, and it is why assumptions are suddenly interesting in a higher-rate market.
Which loans can be assumed?
VA, FHA, and USDA loans are generally assumable with lender approval. Conventional loans generally are not, because most carry a due-on-sale clause that lets the lender demand full payment when the property changes hands. And this is a feature of the loan program itself, not a courtesy your servicer decides to grant. If you are not sure what kind of loan you have, the first page of your mortgage statement or a quick call to your lender answers it in a minute.
Why it helps you as a seller
- More competitive: a low assumed rate makes the monthly payment math look better than a new loan at today's rates, which matters to rate-sensitive buyers.
- A wider buyer pool: buyers who could not qualify for a brand-new loan at today's rates may qualify to assume yours.
- Lower buyer closing costs: the buyer is not paying to originate a brand-new mortgage, which can reduce what they bring to the closing table.
That combination is a genuine marketing edge, and if your loan qualifies, it belongs in your listing. The caveat, and there is always a caveat, is in the fine print below.
What buyers should know
Two things buyers ask me constantly. First, anyone can assume a VA loan, not just veterans. You do not need military service to step into a VA loan; you need to qualify with the lender. Second, the VA assumption funding fee is about 0.5% of the remaining loan balance, a fraction of the funding fee on a brand-new VA loan. The FHA side works differently: a buyer assuming an FHA loan generally must be an owner-occupant, so investors and second-home buyers are out.
The catch sellers need to hear
Let's be honest: an assumption is not a no-brainer. If you have a VA loan and a non-veteran assumes it, your VA entitlement can stay tied to that loan until it is paid off, which can limit your own future VA buying power. Your entitlement is only restored when the assuming buyer is a qualified veteran who completes the substitution of entitlement. That is a real consequence, and it is exactly the kind of thing to understand before you promise an assumption in your listing.
The fine print: lender approval and qualification
Every assumption requires lender approval, and the buyer still has to qualify: credit, income, the whole picture. The lender has to sign off, and the process takes time, so it is not something to promise casually. My advice to sellers is simple. Before you advertise an assumable loan, talk to your lender about whether yours qualifies and what the process involves, then talk to me about how to position it so it helps your sale instead of complicating it.
Mollie says
If you are selling and think you might have an assumable loan, reach out. I will help you figure out whether it is worth leaning into, and how to say it in your listing without overpromising. That is what I am here for: the right move, not just any move.
Written by
Mollie Younger
Ponte Vedra real estate advisor, dual-state broker, mother of a relocated family. 25+ years in real estate, 400+ homes sold. She sees the whole move, not just the house.
About MolliePlanning a move to northeast Florida?
Bring me your situation and I'll bring you the truth: which communities fit, what the budget math looks like, and how the whole move comes together.